Understanding car rental insurance in USA before you arrive at the counter can help you avoid paying twice for protection you already have or accidentally driving without coverage you need.
The right choice depends on your personal auto policy, credit-card benefits, state law, rental agreement, vehicle type and whether you are a U.S. resident or international visitor.
Car Rental Insurance in USA: Quick Overview
| Coverage | Usually Protects Against |
|---|---|
| CDW/LDW | Damage or theft of rental car |
| Liability Coverage | Injury or property damage to others |
| Personal Accident Coverage | Medical expenses for renter/passengers |
| Personal Effects Coverage | Loss or theft of belongings |
| Credit Card Rental Coverage | Usually collision/theft damage |
| Personal Auto Insurance | Depends on your policy |
What Is Rental Car Insurance?
Some products offered at the counter are not technically insurance. A Collision Damage Waiver or Loss Damage Waiver generally reduces or waives your financial responsibility for certain rental-vehicle damage or theft, subject to the rental agreement.
Do You Need Rental Car Insurance?
Maybe, but not necessarily every product. First check whether you already have coverage through personal auto insurance, an eligible credit card, travel insurance or another policy.
1. Collision Damage Waiver / Loss Damage Waiver
CDW or LDW can protect against some or all financial responsibility for damage to or theft of the rental vehicle, depending on the terms. It can be useful when you lack comparable personal or credit-card protection.
2. Liability Insurance
Liability coverage helps protect against injury or property damage you cause to others. Credit-card rental benefits commonly do not replace liability insurance, so review this separately.
3. Personal Accident Insurance
Personal Accident Insurance may provide medical or accident benefits for the renter and passengers. Check whether health or travel insurance already provides similar protection.
4. Personal Effects Coverage
This may protect belongings associated with the rental. Homeowners or renters insurance can sometimes overlap, so verify your existing policy first.
Does Personal Auto Insurance Cover Rental Cars?
Often, but not always. Some personal auto policies extend liability, collision or comprehensive coverage to rentals. Deductibles, exclusions, loss-of-use charges and other costs can still matter.
Does Credit Card Rental Insurance Cover Everything?
No. Credit-card benefits often focus on collision damage or theft of the rental vehicle and may exclude liability, medical costs and personal belongings.
Primary vs Secondary Credit Card Coverage
Primary coverage generally handles an eligible claim before your personal auto policy, while secondary coverage usually applies after other applicable insurance. Always read the current benefit guide for your specific card.
How to Use Credit Card Rental Coverage
- Use an eligible card.
- Pay for the rental with that card.
- Be the primary renter.
- List authorized drivers correctly.
- Decline the rental company’s CDW when required by the card benefit.
- Follow vehicle, country and rental-duration rules.
Rental Car Insurance for Tourists Visiting USA
International travelers should verify whether home-country insurance applies in the United States and whether their credit card covers U.S. rentals. Liability deserves special attention.
For documentation and licensing guidance, read our guide to renting a car in USA as a tourist.
What Happens if You Damage a Rental Car?
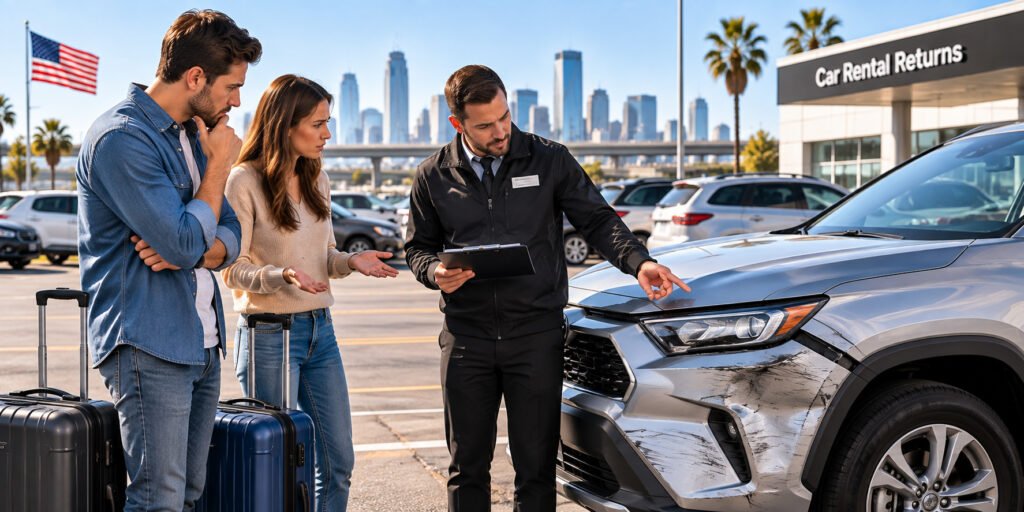
Make sure everyone is safe, contact emergency services when necessary, follow reporting requirements, notify the rental company, document the scene and contact the applicable insurer or credit-card benefit administrator promptly.
How to Decide What Coverage You Need
- Call your auto insurer.
- Read your credit-card Guide to Benefits.
- Check travel and other policies.
- Identify liability, collision, medical and property gaps.
- Make the decision before reaching the rental counter.
Rental Car Insurance Checklist
- Liability limits
- Collision/comprehensive coverage
- Credit-card benefit
- Primary vs secondary status
- Deductible
- Loss of use
- Towing
- Vehicle exclusions
- Rental-duration limits
- Geographic restrictions
Frequently Asked Questions
Do I need rental car insurance in USA?
It depends on your existing coverage. Verify personal auto insurance and credit-card benefits before declining rental protection.
Does my credit card cover rental cars?
Many cards provide collision or theft protection, but terms vary and liability is commonly excluded.
Is CDW the same as insurance?
Not exactly. It is generally a contractual waiver of financial responsibility for certain rental-vehicle damage or theft.
Should international tourists buy rental insurance?
They should first verify home-country insurance, credit-card coverage and liability protection, then fill any meaningful gaps.
Final Verdict
Do not automatically buy every product at the counter, and do not automatically decline everything because you have a credit card. Start with your personal auto insurance, review your card benefits, identify gaps and decide before pickup.
For related planning, compare the best car rental companies in USA, cheapest car rental companies in USA, and best airport car rental companies in USA.
Other Articles
How to Rent a Car in USA as a Tourist: Complete 2026 Guide
[…] Car Rental Insurance in USA (2026): What Coverage Do You Really Need? […]
[…] Car Rental Insurance in USA (2026): What Coverage Do You Really Need? […]